Stablecoin quote, collateral and reporting basis
Do not collapse token balances, issuer information, collateral treatment and fiat valuation into a single dollar label.
The token label is not the complete claim
A quote token, settlement token and collateral token may have different roles. Record network and contract identity where applicable, and distinguish exchange ledger representation from external wallet asset. A dollar-like symbol cannot establish fiat cash, issuer redemption access or a market peg. Issuer transparency describes its own reported reserve context, not every venue balance or account permission. This desk has not independently audited reserves or measured redemption. The guide asks for specific source objects instead of inventing a universal financial or legal assurance from a familiar stablecoin name.
Collateral has its own account rules
A reporting amount does not tell how collateral is valued for margin or whether transfers are currently available. An actual account needs its effective collateral, haircut, conversion and eligibility sources. The settlement lens excludes margin and liquidation entirely. Its linear branch defines quote settlement under a manually entered label; that is not proof of a real exchange's collateral policy. Inverse mode uses a base-asset coin amount with a declared reporting multiplier. Neither branch authenticates issuer, network, custodian, account balance or the ability to withdraw the represented asset.
Keep conversion assumptions visible
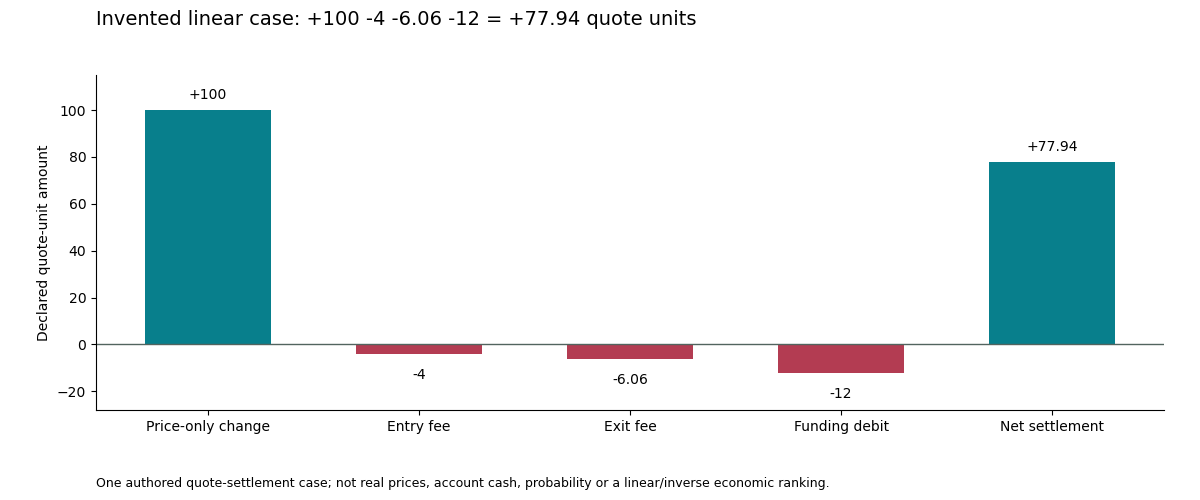
A coin net multiplied by a chosen quote-per-coin rate gives a hypothetical reporting value. It does not execute a conversion, pay a spread or include a withdrawal fee. A rate of one is an identity convention when the worksheet already expresses quote settlement; it is not an asserted peg for a token to fiat. Actual conversion requires source time, executable quantity, fee asset and account policy. Preserve those missing objects rather than presenting a neat dollar amount as complete economic evidence. The chart deliberately uses only one declared quote-unit example.
Historical strategy records need the original basis
A genuine historical study must retain token/network versions, effective collateral rules and the reporting convention used throughout the eligible period. Repricing only favourable outcomes with a later rate changes the study. Delisting, migration, custody and access events need original records rather than synthetic repairs. These pages provide no observed token price, depeg frequency or account stress result. The authored valuation alternatives teach what changes when a multiplier changes. They cannot establish solvency, future parity, personally suitable collateral or independently validated trading returns.
Fictional crypto evidence case
An invented inverse case has 19.832 settlement units. A reporting multiplier of 125 gives 2,479 quote units; a multiplier of 100 gives 1,983.2. The unit balance is unchanged. There is no real conversion, reserve claim, fiat amount or account collateral permission in that teaching comparison.
| Object | Record | Bounded finding |
|---|---|---|
| Settlement | 19.832 declared coin | Balance assumption |
| Reporting | 125 or 100 quote per coin | Separate valuation |
| Collateral | No terms supplied | Not calculated |
Primary references and scope
Source review: 14 October 2026. Official mechanism descriptions are not this desk's paid-account test, independently captured fills or vendor-return audit.