Crypto settlement and outage workbook
Seven invented settlement cases and an eight-step paper drill. No real venue data, order, account or incident is represented.
Read the full object before its result
The amount packet fixes a declared quote notional or face, two assumed prices, fee basis points and signed whole-position settlement funding. Linear settlement is quote units; inverse settlement is base-asset coin units. Both retain their exact labels and missing contract identity. Actual fills and probabilities are null. The cases are selected arithmetic branches, not a population of observed trades or evidence of a profitable strategy. Prices of 100, 101 and 125 are invented even where the label says BTC. The intended lesson is how units survive a calculation, not what a real market is likely to do.
The independent Python Decimal calculation and the browser's decimal.js implementation use the same declared equations but separate code. Agreement verifies software amounts. It does not certify current product specifications, fee tariffs, contract lots or eligible positions. The reference base exposure can be fractional and is not a validated number of contracts. No live market route, liquidity, leverage, collateral, liquidation, borrowing, tax or partial-close policy is supplied. Real instruments require their own complete source and authorised research route before stronger economic language is used.
Linear: changing exit value changes its fee base
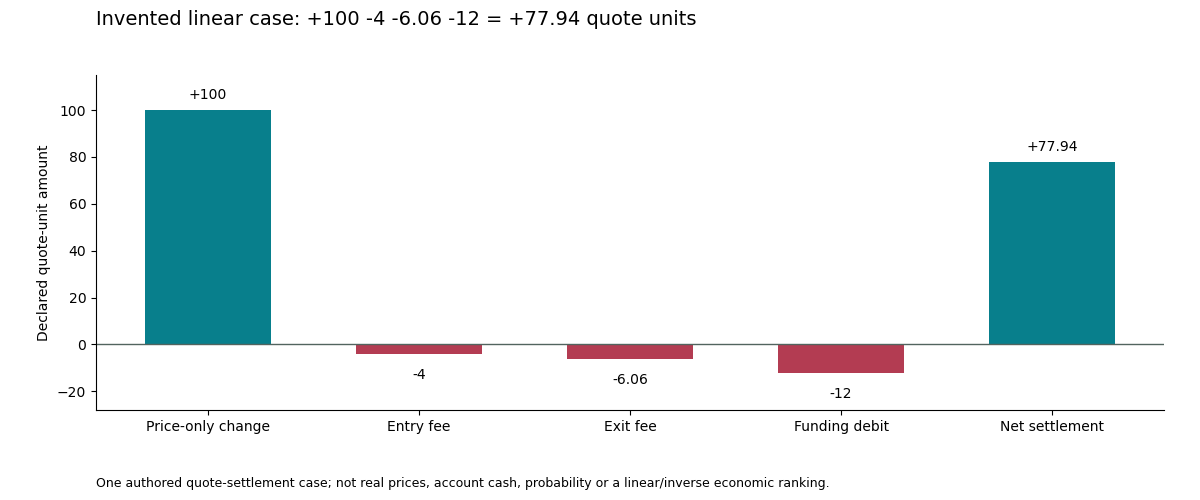
With invented initial quote notional 10,000 and entry 100, reference base exposure is 100. Exit 101 produces 100 quote-unit gross for long. Four entry fee basis points cost four. Six exit fee basis points apply to exit value 10,100 and cost 6.06. Signed funding negative 12 leaves 77.94 net quote units. Linear quote valuation must be one under this contract. The flat case has zero gross and net negative 22; the short case has negative 100 gross and net negative 122.06. Those alternatives are authored, not successive trades or a calibrated loss distribution.
The original fixed-notional budget remains available. Match four/six fees, zero slippage, six funding events at two paid basis points and a one-percent move to get 78 there. The 0.06 difference identifies its fixed exit fee base. Its original default is 74 under different fee and slippage inputs; that is not the matched comparison. Neither result is a superior contract or vendor. Actual fees need unique fills, roles, assets, effective tiers and original reporting policy. A calculation cannot recover those missing records from an attractive net amount.
Inverse: coin amount and quote valuation differ
The invented inverse long keeps quote face 10,000, entry 100 and exit 125. The reciprocal-price equation gives 20 settlement coin units. Entry fee is 0.04 coin and exit fee is 0.048 coin, with funding negative 0.08 coin. Net is 19.832 coin; a declared quote-per-coin valuation of 125 gives 2,479 quote units. Short under the same assumed inputs gives negative 20.168 coin and negative 2,521 quote units. These are deliberately different exposures from the one-percent linear case, so no economic winner or margin return can be inferred from comparing their headline amounts.
Changing only inverse valuation from 125 to 100 leaves 19.832 coin unchanged and gives 1,983.2 quote units. This is reporting arithmetic, not an executed conversion or fiat peg claim. The plot therefore uses only the default quote-settlement components, not a shared axis for incomparable coin and quote values. Contract switch clears the funding and valuation fields to prevent reinterpreting quote cash as coin. A genuine account comparison additionally needs actual specification, position quantities, collateral, cost vintages and reporting conversion sources. No account history was supplied for any case.
A funding credit is an alternative assumption
Replacing the default linear negative-12 debit with a positive-three credit gives 92.94 net quote units. The 15-unit change is declared whole-position cash, not a forecast rate or a guaranteed six-event settlement. The original cost worksheet uses the opposite sign convention for its per-event paid funding rate. Preserve sign, unit and inclusion when transferring any assumption. Final account settlements are different sources from earlier indicative values. Neither tool fetches a funding calendar or proves actual position membership. A real result must retain every final event rather than selectively using favourable estimates.
All seven settlement cases
| Case | Convention | Settlement label | Gross | Fees | Signed funding | Net settlement | Quote valuation |
|---|---|---|---|---|---|---|---|
| Linear favourable move with costs | linear | USD | 100.0 | 10.06 | -12.0 | 77.94 | 77.94 |
| Linear flat price with cash debits | linear | USD | 0.0 | 10.0 | -12.0 | -22.0 | -22.0 |
| Linear short adverse price | linear | USD | -100.0 | 10.06 | -12.0 | -122.06 | -122.06 |
| Inverse long, coin settlement | inverse | BTC | 20.0 | 0.088 | -0.08 | 19.832 | 2479.0 |
| Inverse short, same assumed prices | inverse | BTC | -20.0 | 0.088 | -0.08 | -20.168 | -2521.0 |
| Same coin amount, different quote valuation | inverse | BTC | 20.0 | 0.088 | -0.08 | 19.832 | 1983.2 |
| Linear alternative funding credit | linear | USD | 100.0 | 10.06 | 3.0 | 92.94 | 92.94 |
Paper drill: unknown request is not rejected request
The eight relative steps below are entirely authored. They do not describe an actual outage, account, venue or recovery. A fictional request intends ten units; a timeout leaves its outcome unknown. An evidence query can itself remain pending. Only a later invented acknowledgement changes the teaching state to accepted. That acknowledgement still is not a unique fill. The actual stronger source would be the selected account/order evidence within the endpoint's real scope, not a blind resend. This publication performs no such request and supplies no live retry procedure or credential.
The drill then declares four executed units and six remaining. A later intention to cancel the remainder does not itself establish cancellation. The authored cancellation acknowledgement removes the remainder while four open position units survive. The final fictional position snapshot still shows those four units; no closing fill was invented. Repeated cumulative status notifications must not be summed as additional executions. An authentic recovery would need complete unique fills and position state with accountable cloud ownership. The drill's completion means every source question is visible, not that a real account was made flat or safe.
Keep education distinct from account operation
The website never signs orders, changes stops, watches a position or owns production exits. Native minute execution, whole-position rules, maximum holding and established hypothetical research-fill policy remain unchanged. Actual instrument tasks still require their authorised factory and independent master, including a correctly certified asset integration. Correct amount equations and paper source states cannot replace that completion. Production publication remains cloud-owned with personal computers off; temporary local verification creates no scheduler or operational fallback. No uptime statistic, incident probability, actual account result or paid customer experience is fabricated.
The downloadable JSON and CSV contain every selected case and every paper step, including earlier unknown values. Blank actual fields remain absent rather than acquiring plausible timestamps or balances. The exact dependency licence is available for decimal.js but grants no third-party market-data right. The original ten-field workbench can retain genuine source requests separately. Current offer, supported contract, fee role and account permission require authentic selected terms. Use the packet to identify what is missing, not as an independent endorsement or evidence that a vendor, account or strategy passed a financial audit.
Eight complete relative paper steps
| Step | Declared source | Request state | Executed | Remaining | Open position | Next evidence |
|---|---|---|---|---|---|---|
| 1 | Fictional client intention | requested | unknown | unknown | unknown | Original selected request identity and endpoint contract |
| 2 | Fictional timeout | unknown | unknown | unknown | unknown | Authoritative selected account/order state; do not assume rejection |
| 3 | Fictional query pending | unknown | unknown | unknown | unknown | Authentic query response within its actual product/history scope |
| 4 | Fictional acknowledgement | accepted | 0 | 10 | 0 | Unique execution and later state sources; acknowledgement is not a fill |
| 5 | Fictional partial execution declaration | partially-executed | 4 | 6 | 4 | Complete unique executions; do not sum repeated cumulative messages |
| 6 | Fictional remainder-cancel intention | cancel-requested | 4 | 6 | 4 | Cancellation result and separate position source |
| 7 | Fictional remainder cancellation acknowledgement | remainder-cancelled | 4 | 0 | 4 | Actual current position; cancelled remainder does not close executed units |
| 8 | Fictional position snapshot | remainder-cancelled | 4 | 0 | 4 | Actual owned position lifecycle remains required; no closing fill supplied |