Crypto funding: forecast vintages are not settled cash
Track product calendars, position eligibility and final settlement before interpreting a funding forecast as an account cost.
An estimate and a cash event answer different questions
A displayed forecast describes an estimate under its product's current rules. A final settlement is a dated account event with amount, asset and eligible position scope. Save forecast observation, forecast target event and final settlement as separate objects. Updating a historical file with the final value can leak later information into a prior decision. The desk supplies no actual funding series. Current official product mechanics explain context but cannot establish an earlier account's event membership or cash. Do not infer a universal schedule from one venue's example.
Declare the sign and quantity convention
The original friction budget treats positive funding rate as paid cost and multiplies entered notional by rate and event count. The new lens receives signed whole-position settlement cash, positive for credit and negative for debit. Those contracts are intentionally different. Linear funding is quote units; inverse funding is coin units under the worksheet convention. A change of contract clears the unit-sensitive fields. A real funding reconciliation needs actual event quantity, settlement asset, cash sign and selected account rules rather than an amount copied between incompatible forms.
Membership is an operational source
A holding window alone may not settle every product's funding eligibility. Original account position and effective calendar need their actual rules, including changes and maintenance where relevant. A forecast that looked favourable earlier is not a guaranteed receipt. Save the event record alongside executions, fee cash and conversion policy. If the original source is unavailable, mark that component unknown rather than assuming six equally spaced debits for a real trade. The invented six-event comparison remains a teaching approximation and cannot reconstruct a subscriber statement.
Inspect funding without reopening selection
An authentic study freezes rule identity and one exit before its evaluation. Funding measurements can assess that fixed economic contract, but a favourable funding period must not select a new entry or retroactively improve the chosen window. Keep inspected periods and failed variants in the trial ledger. The workbook completes seven manually chosen cases only; they are not calibrated distributions or a carry strategy. A correct positive credit calculation establishes neither persistent edge nor account access. Actual market research still needs eligible data and an independent master.
Fictional crypto evidence case
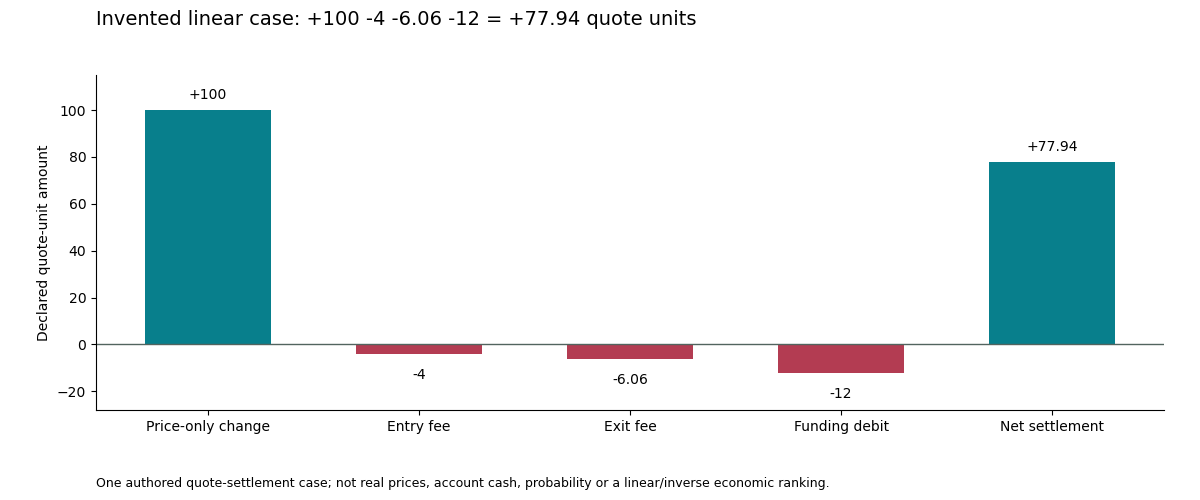
Invented linear default uses signed funding negative 12 quote units, not a live rate. Replacing it with positive three raises net from 77.94 to 92.94 while every other assumption is unchanged. The difference is a declared 15-unit cash change, not a forecast of future funding or evidence that a selected contract pays a trader.
| Object | Record | Bounded finding |
|---|---|---|
| Estimate | No real vintage supplied | Not settlement |
| Default cash | -12 quote units | Invented debit |
| Alternative | +3 quote units | Invented credit |
Primary references and scope
Source review: 14 October 2026. Official mechanism descriptions are not this desk's paid-account test, independently captured fills or vendor-return audit.